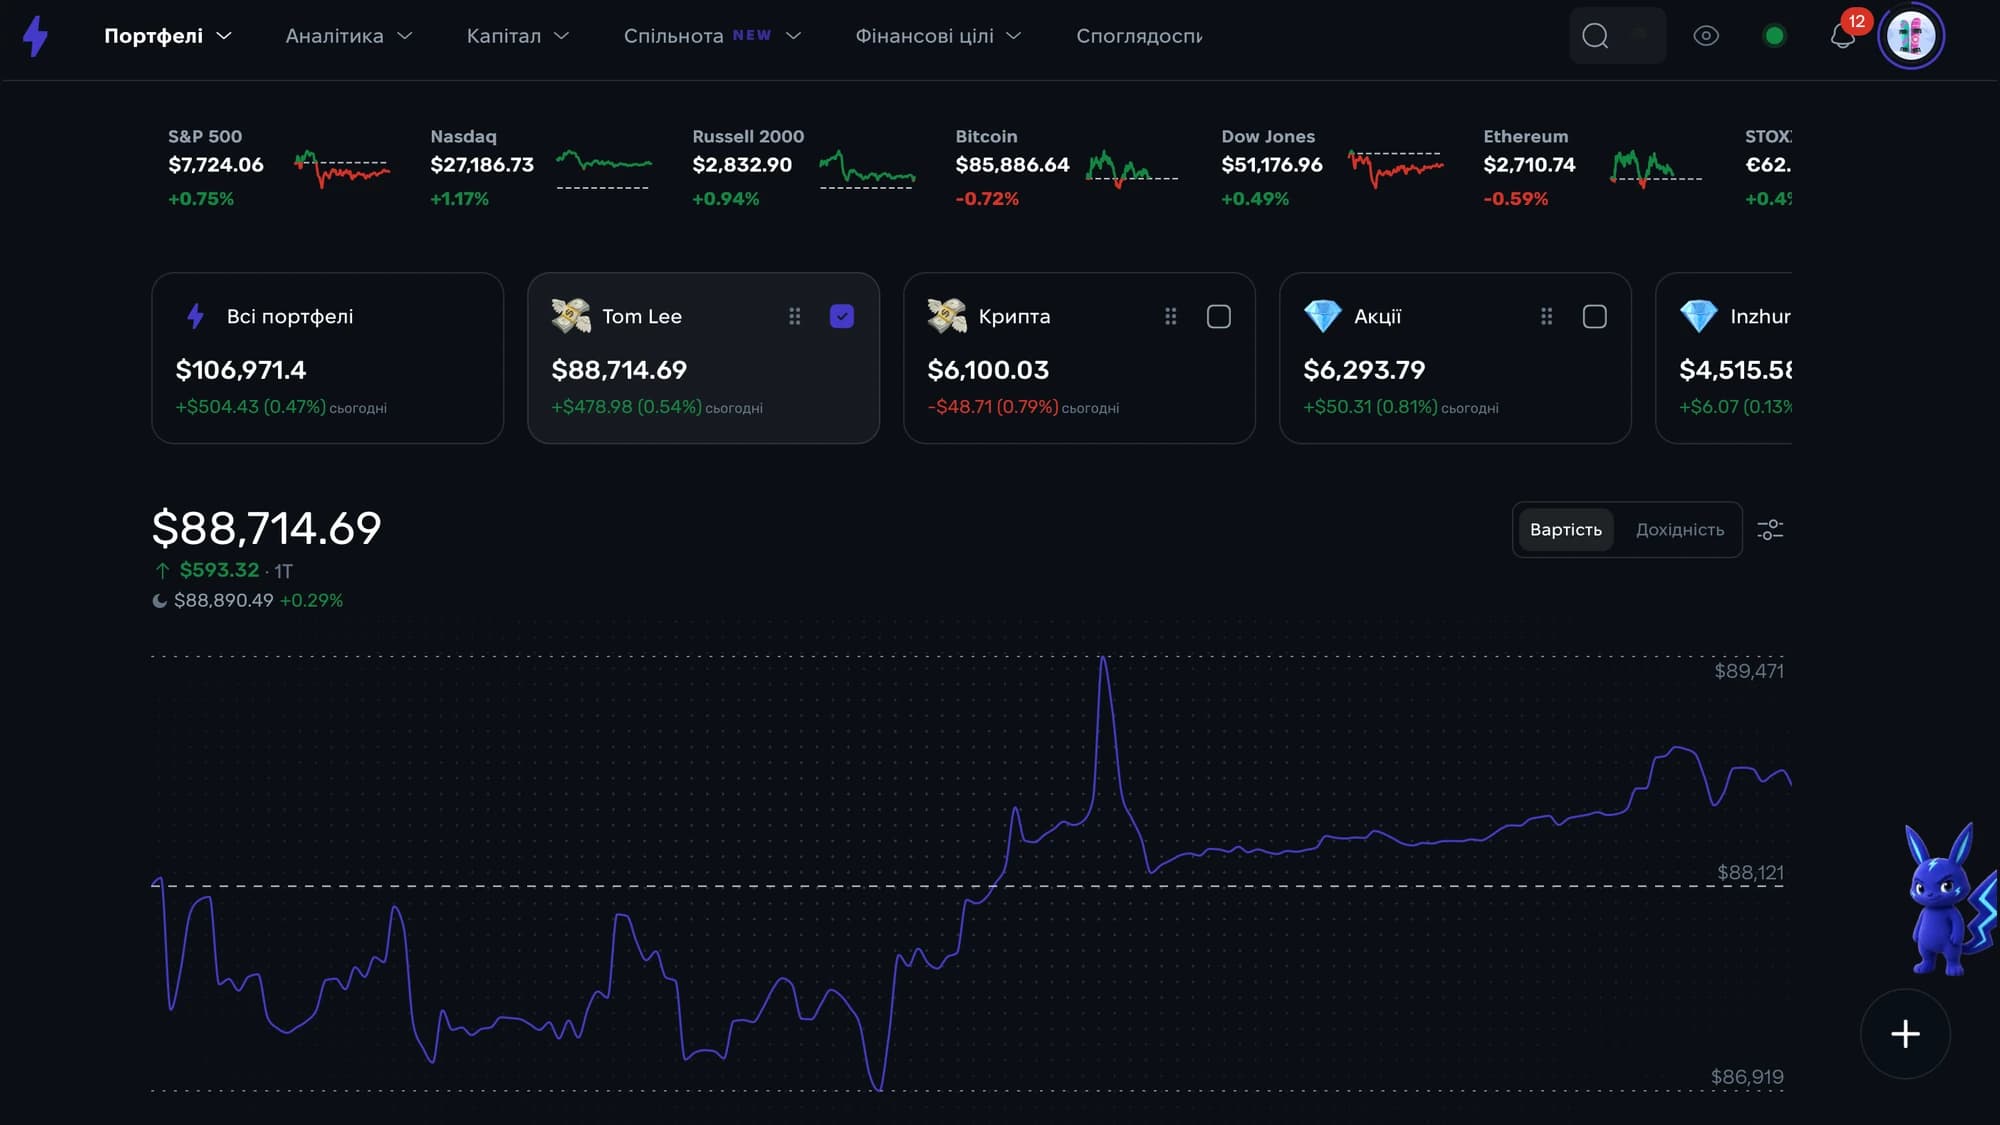
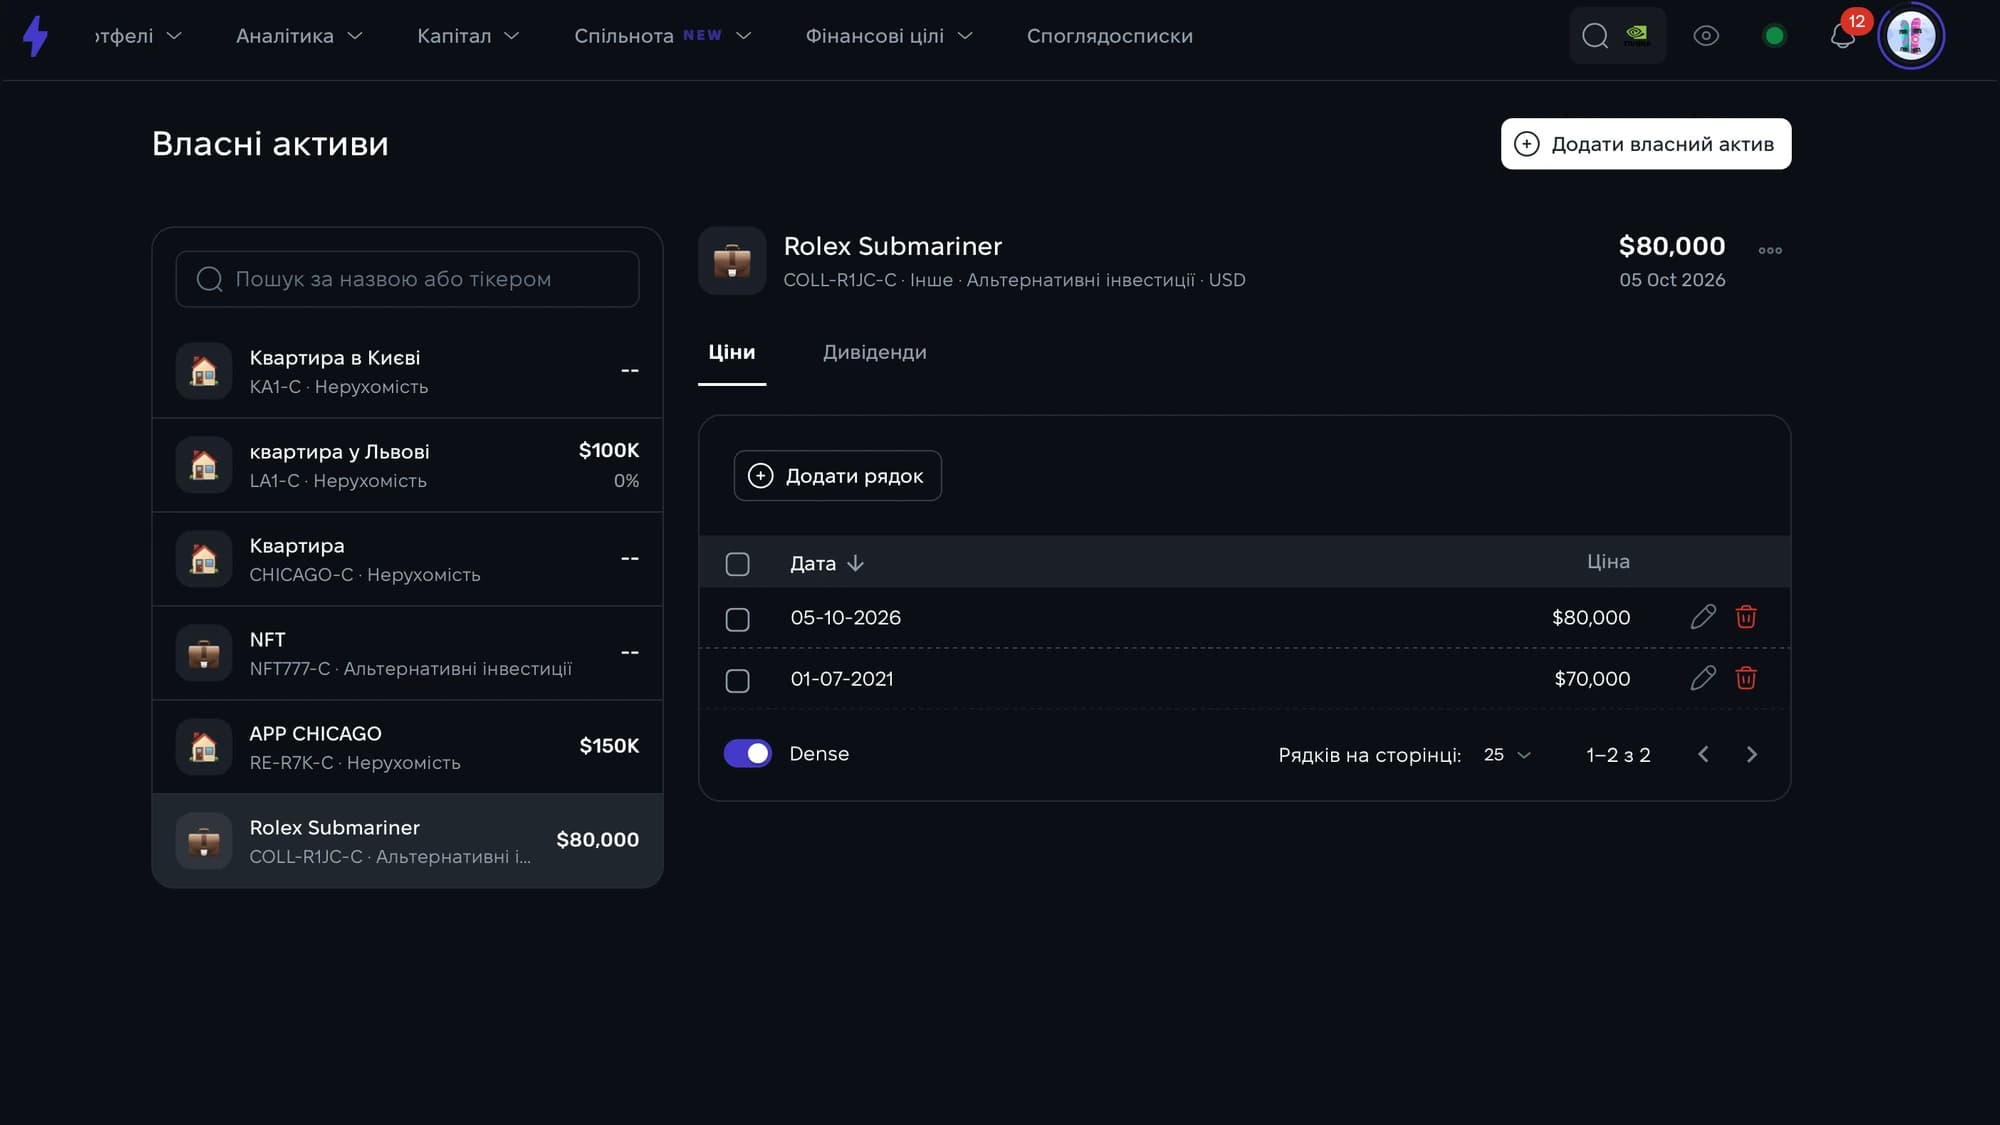
Owning many assets does not tell you how much capital you have or how it is structured. An apartment, brokerage account, deposit, business stake and crypto wallet can add up to a large sum, but some of these assets may have been bought with borrowed money. To see the real picture, you need one system that brings together what you own and the liabilities used to finance it.
The basic logic comes down to two formulas:
| Assets = liabilities + equity. Net worth = assets − liabilities |
|---|
Once net worth is calculated, break it down by asset class, currency, liquidity, risk, geography and goals. This breakdown reveals the real structure of your capital.
What capital is and what its real structure means
Capital is a collection of resources that have economic value and can generate income. For a private investor, it includes everything they own, from money in an account to property and businesses. Academic distinctions between a company's share capital, reserve capital and other categories are not needed here.
Distinguish two views. The first shows what you have: your asset mix. The second shows how it is financed: with your own money or borrowed capital.
| What you own | How it is financed |
|---|---|
| Apartment, ETFs, Ukrainian government bonds (OVDP), deposit, car, business stake | Equity + liabilities, such as mortgages and loans |
Capital structure describes the balance between your own and borrowed funds that finance your assets, as well as the distribution of those assets across classes, currencies and risks. An asset portfolio and capital structure are related, but they are not the same thing.
Assets, liabilities and equity: what is the difference?
An asset is something with economic value. A liability is an amount you must repay or pay. Equity is the portion of your assets that remains after all liabilities are subtracted.
| Measure | What it shows | Example |
|---|---|---|
| Assets | what the investor owns | ETFs, an apartment, Ukrainian government bonds |
| Liabilities | what must be repaid | mortgage, loan |
| Net worth | the owner's actual share | assets minus debts |
Equity on a company's balance sheet appears on the financing side and represents the owners' contributions and accumulated profits. Accounting concepts such as the composition of fixed capital serve corporate reporting. An investor's personal balance sheet follows the same logic but is simpler: you list assets and debts, and the difference is your net worth.
How capital structure differs from investment portfolio allocation
Portfolio allocation answers the question, "What is the money invested in?" Capital structure also asks, "Whose money is it: yours or borrowed?"
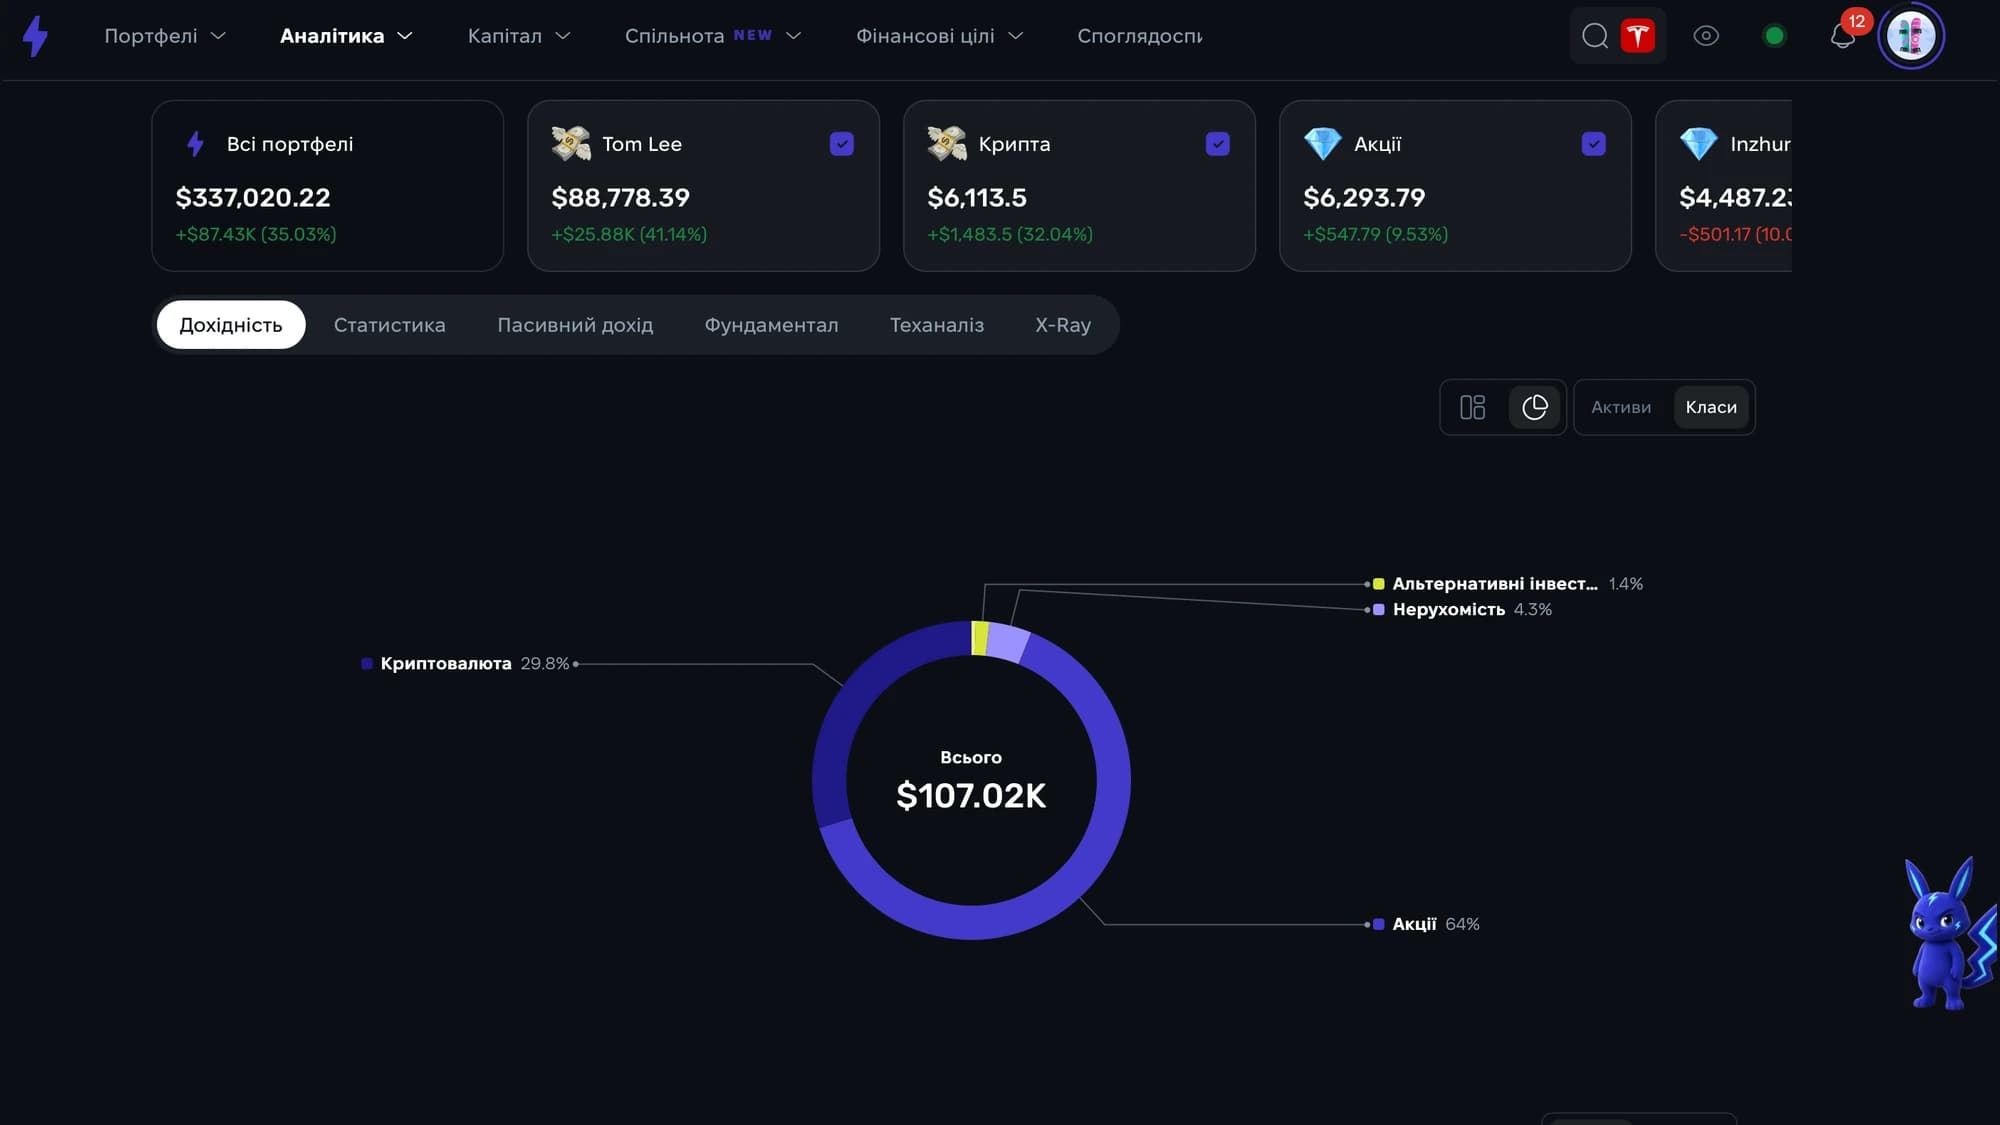
For example, two investors hold identical portfolios worth 2 million UAH. The first invested their own money. The second borrowed half the amount. Their portfolios are identical, but their capital structures differ: the second investor has only 1 million UAH of their own money in the portfolio, so a market decline hits their equity twice as hard.
Why a large number of assets can distort the picture
Someone sees real estate, a brokerage portfolio, a car, a business, a deposit and government bonds, then adds up their full value. However, some of those assets may:
- have been bought on credit;
- have associated liabilities;
- be illiquid;
- have inflated or outdated valuations;
- be duplicated across different services;
- belong to several owners.
So "I have assets worth 10 million" does not mean "my net worth is 10 million."
Gross asset value versus your actual equity
An apartment is worth 5 million UAH, with 3 million UAH outstanding on the mortgage. Its gross asset value is 5 million UAH. Your net worth in this asset is:
5 million UAH − 3 million UAH = 2 million UAH
The second number shows the portion of the apartment's value that belongs to you without debt financing.
What makes up a private investor's capital structure
Personal capital extends beyond a portfolio of stocks, ETFs or bonds. For a complete picture, collect all assets with economic value and all financial liabilities. The composition of capital usually looks like this:
| Category | What it includes | What to record | What to watch |
|---|---|---|---|
| Cash assets | cash, bank accounts | amount, currency, bank | currency and bank concentration |
| Securities | stocks, ETFs, Ukrainian government bonds, other bonds | current value, currency, broker | market risk and concentration |
| Real estate | apartments, houses, land | current valuation, currency, debt | mortgage and low liquidity |
| Business interests | stakes in companies | ownership share, estimated value | difficulty of accurate valuation |
| Alternative assets | cryptocurrency, gold and similar assets | value, where they are held | volatility and liquidity |
| Liabilities | loans, mortgages, other borrowing | outstanding balance, rate, term | impact on net worth |
How contingent obligations affect your real capital structure
Some obligations are not debts today but may become debts tomorrow:
- Guaranteeing someone else's loan. If the borrower does not pay, you may have to repay the debt.
- A personal guarantee for a business loan. Company problems can become your personal debt.
- Signed financial commitments. For example, a contract to buy a newly built home with a payment schedule.
- Potential tax payments. Tax on profits from selling shares or property that has not yet been paid.
- Other contracts that may cause a significant future cash outflow.
These do not always need to be subtracted from net worth as ordinary debt, but they should be recorded separately as potential risks.
How to calculate your real capital structure: step by step
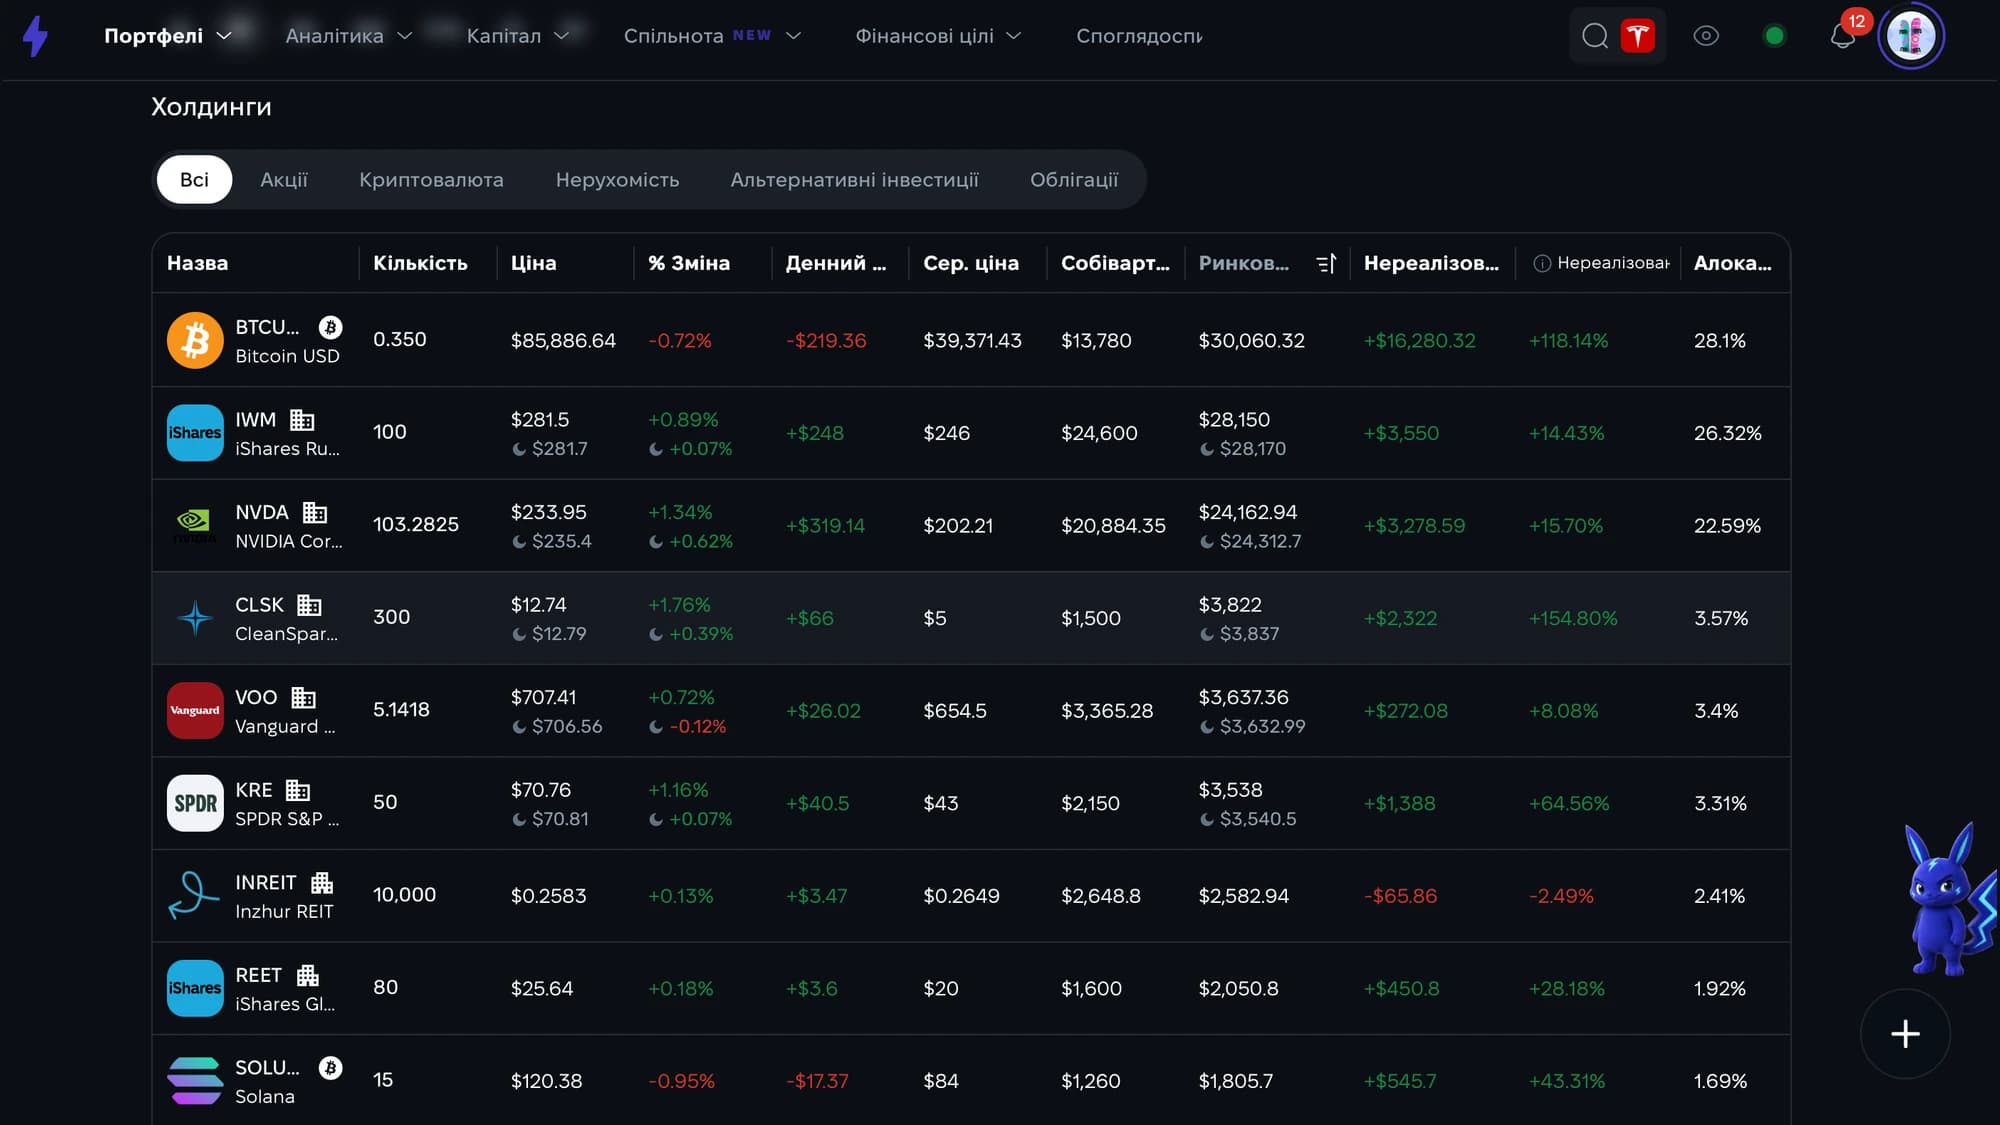
Step 1. Gather all assets in one place
Collect information from banks, brokers and crypto wallets, along with property documents and details of business stakes. Whether you use a spreadsheet or an app matters less than keeping one register.
Step 2. Update asset values
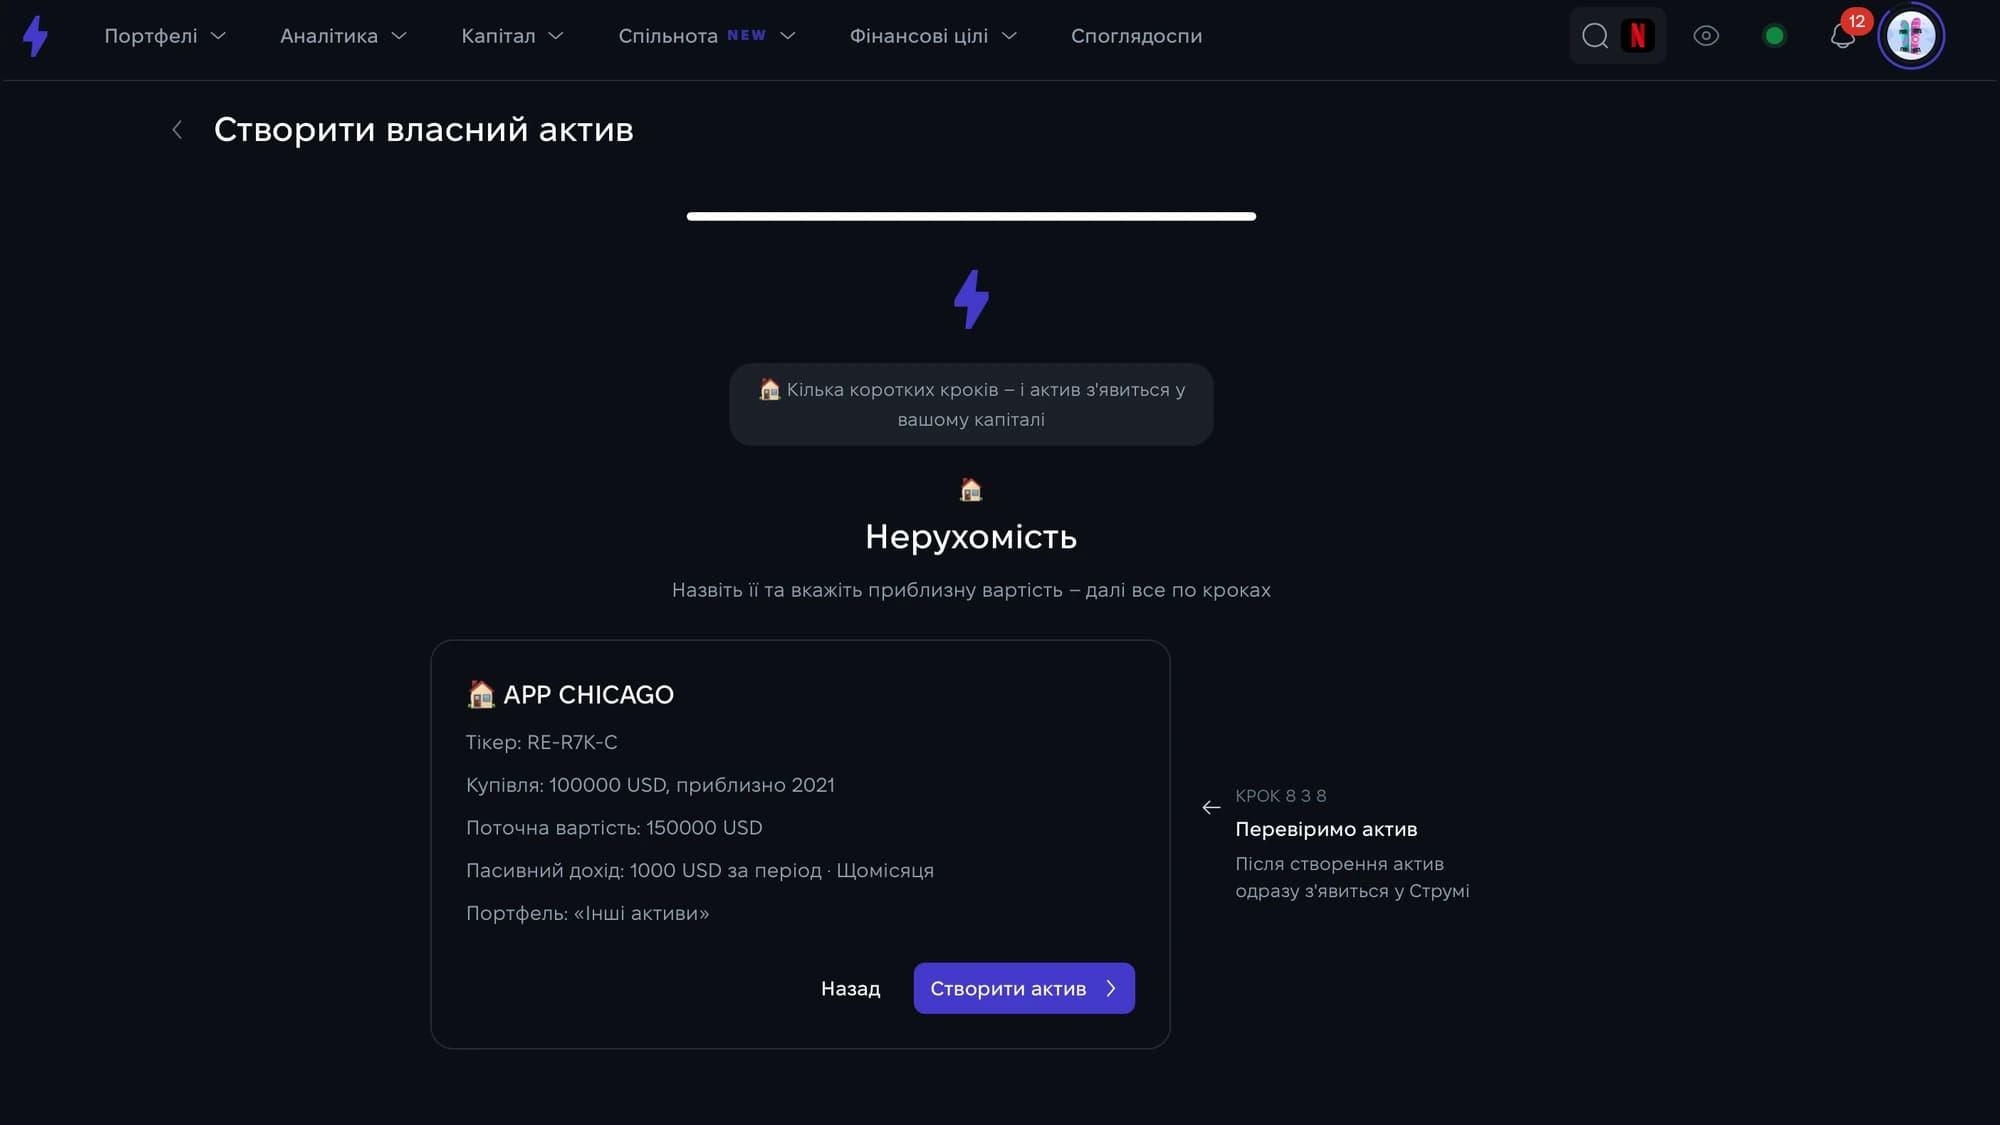
Do not mix purchase price, face value and current market value. Analysis requires an up-to-date economic valuation. For illiquid assets such as property or a business, record the valuation method and date.
Step 3. Convert everything into one base currency
A portfolio in hryvnias, dollars and euros cannot be compared without conversion. Choose a base currency, but also keep each asset's original currency: you will need it to analyse currency exposure.
Step 4. Add all liabilities
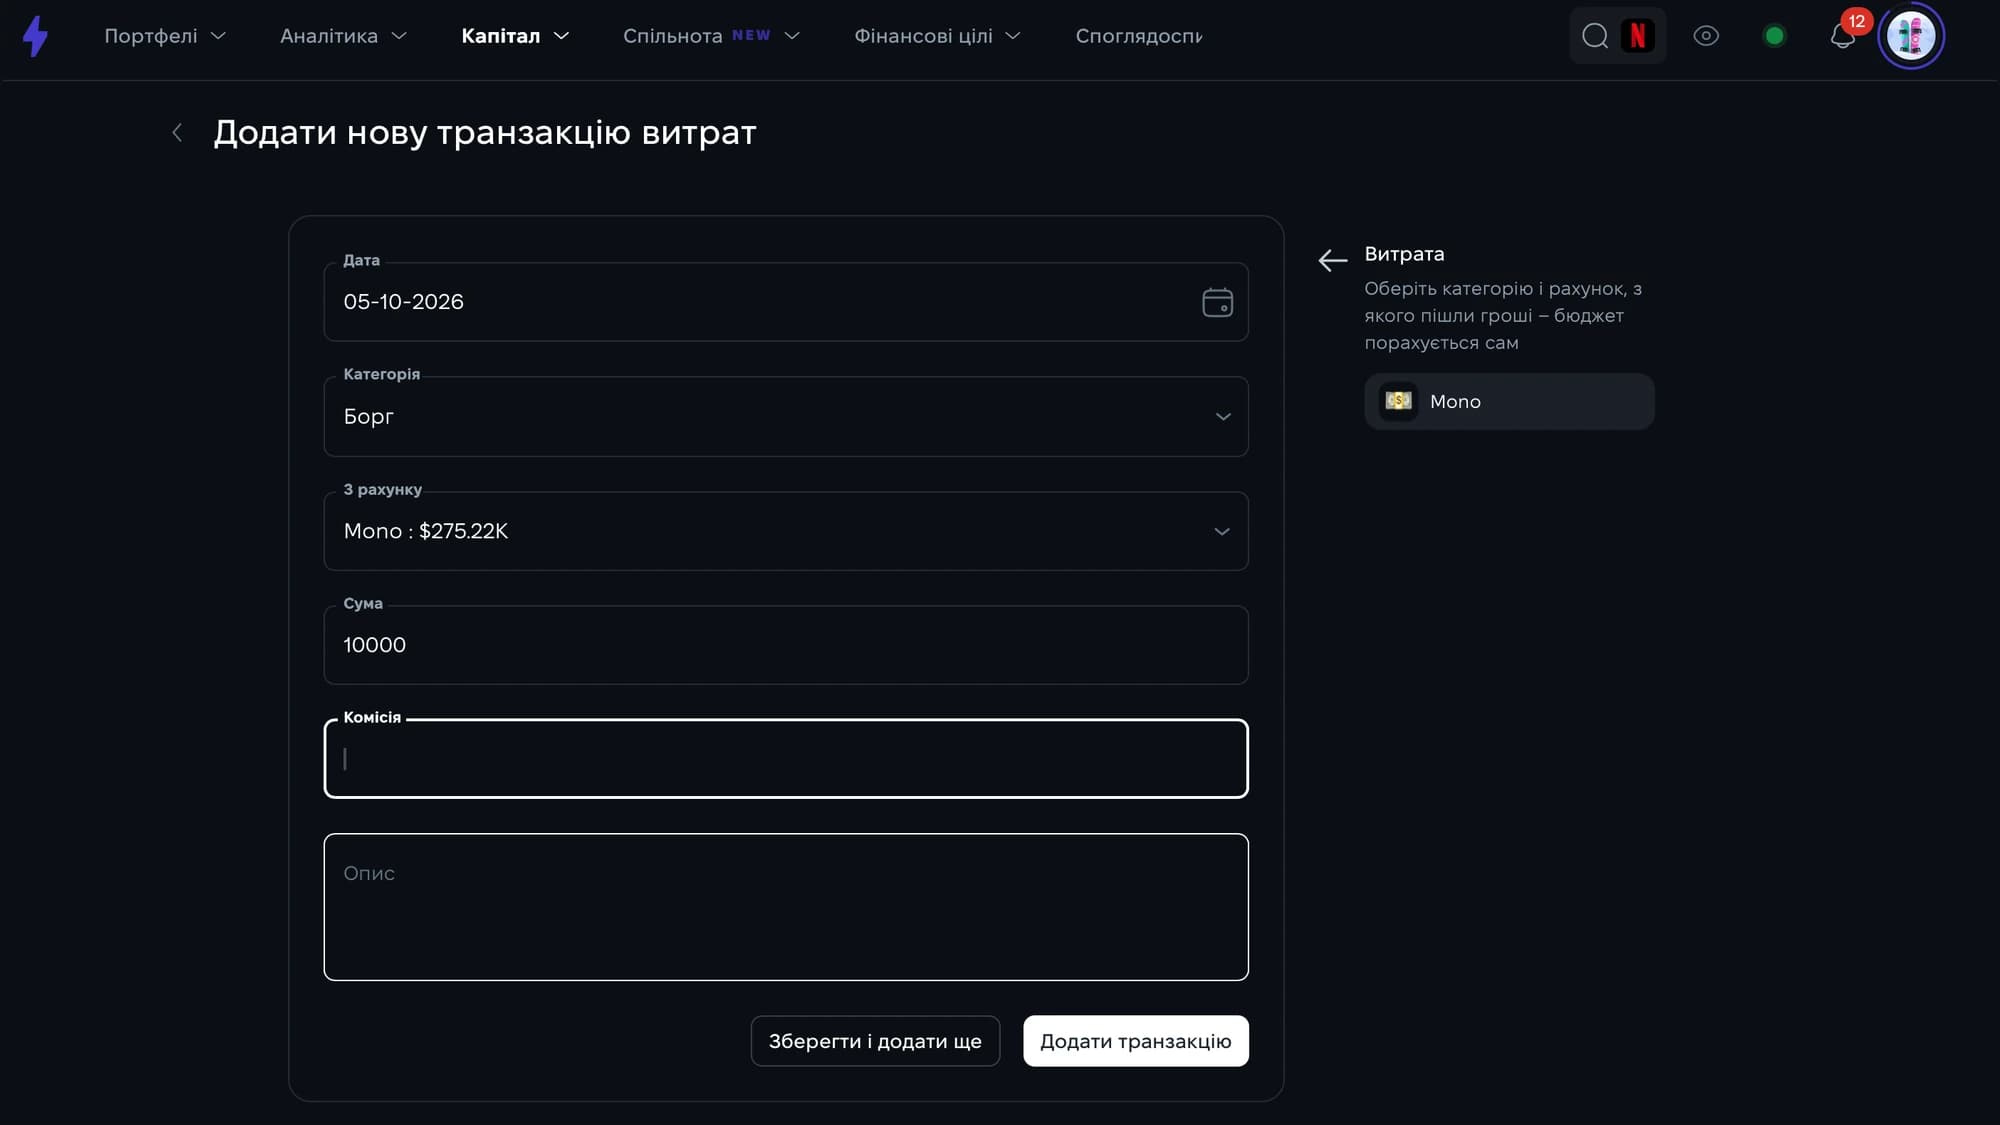
Do more than record the total debt. Link each loan to the asset it finances and record the repayment term and interest rate.
Step 5. Calculate net worth
Net worth = total asset value − total liabilities
For example: an apartment worth 5 million UAH, a brokerage portfolio of 1.8 million UAH, deposits and government bonds worth 0.9 million UAH, and a car worth 0.7 million UAH. Total assets are 8.4 million UAH. A mortgage of 3 million UAH and a car loan of 0.3 million UAH give net worth of 8.4 − 3.3 = 5.1 million UAH. Also calculate the net position for each asset financed with debt. Strum's budget and capital section does this automatically, combining accounts, portfolios and debts into one view of net worth.
Step 6. Break down capital across key dimensions
Calculating the total is only the start of the analysis. Break down your capital by:
- asset classes;
- currencies;
- countries;
- liquidity;
- risk;
- counterparties, such as banks, brokers and exchanges;
- investment goals;
- time horizon;
- equity and debt financing.
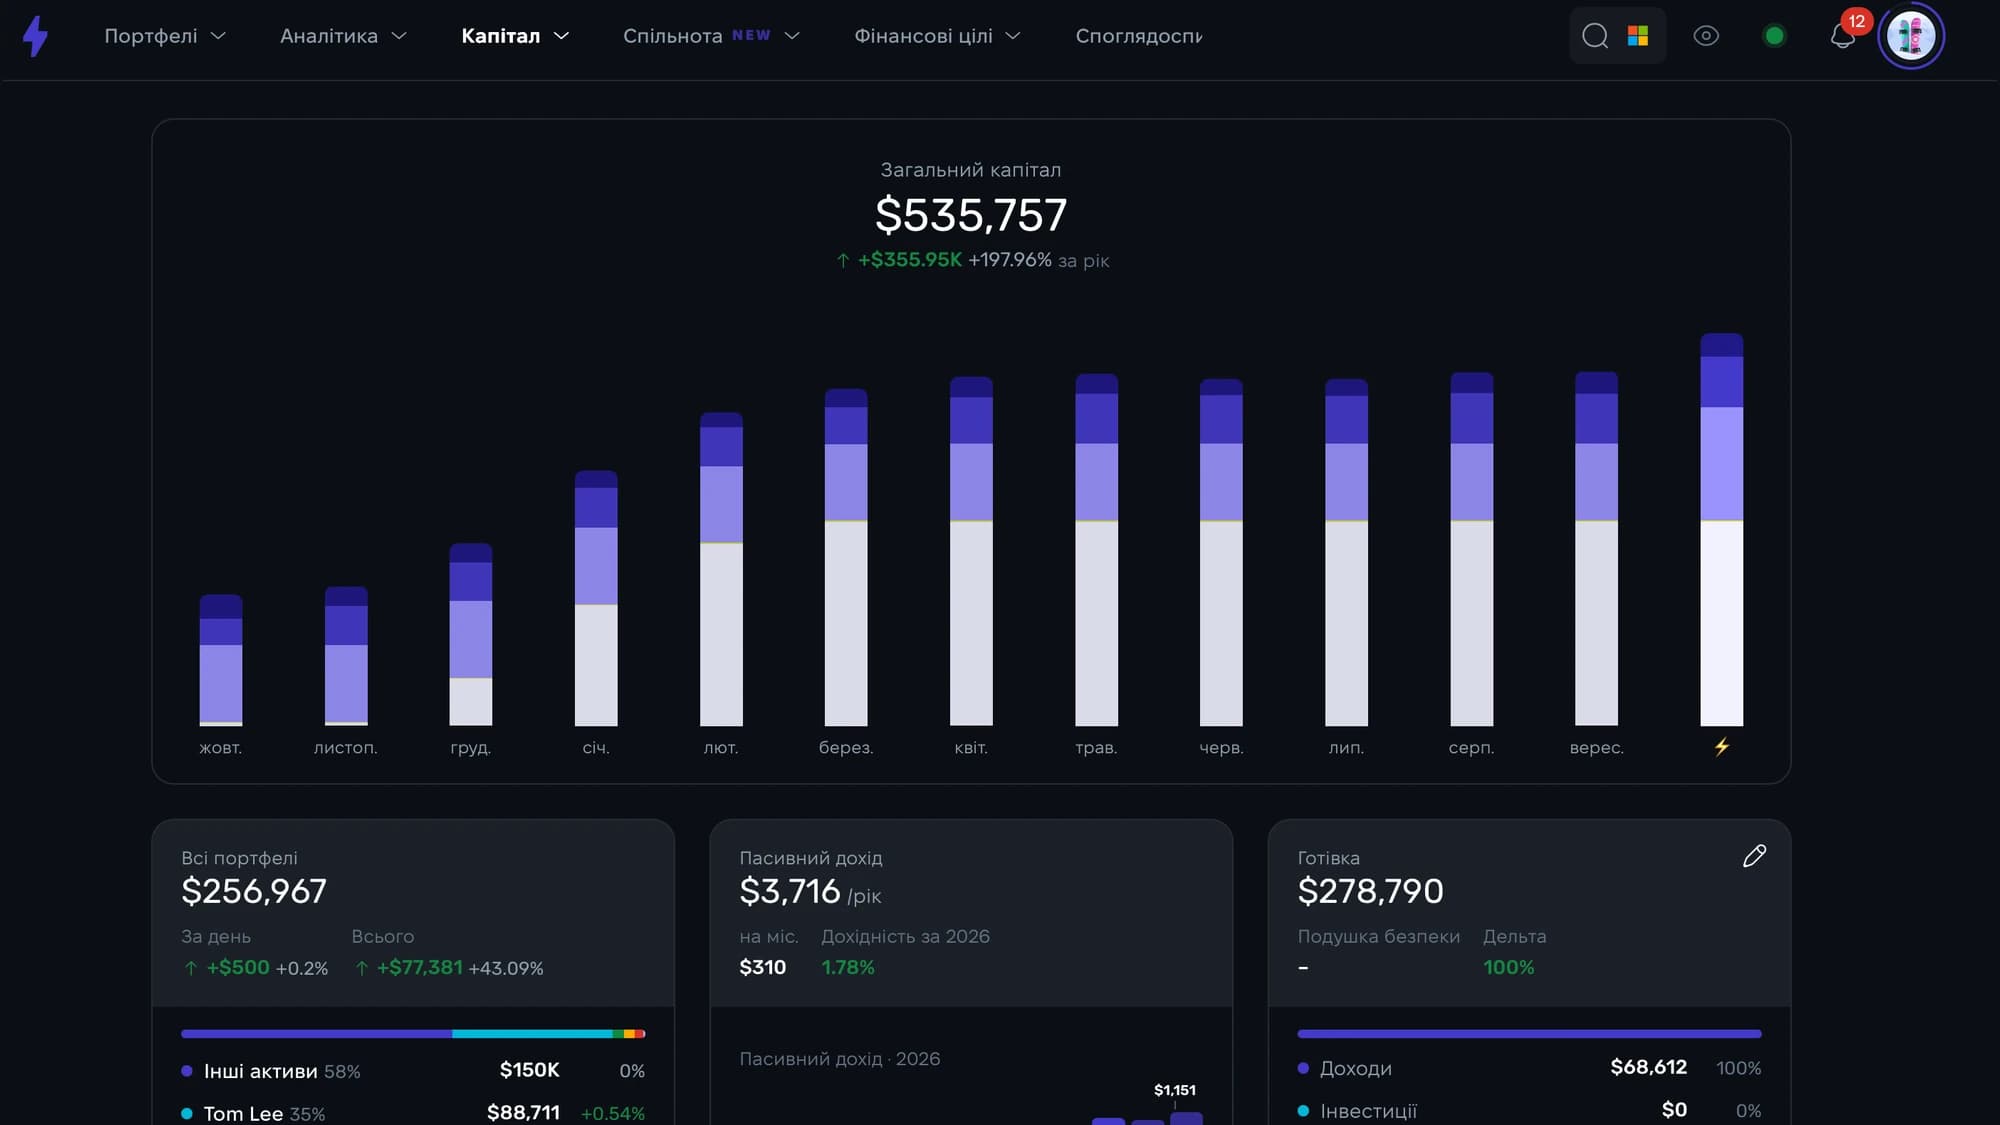
Step 7. Compare the current structure with the target
Identify:
- where concentration exceeds the desired level;
- which assets do not fit your goals;
- where leverage is high;
- where liquidity is insufficient;
- whether price movements have changed the structure.
There are no universally correct percentages here: your own plan is the benchmark.
How to organise dozens of assets
Use one category system
The same apartment cannot be classified as real estate in one spreadsheet and investments in another. Define categories once and use them consistently.
Avoid double counting
Common examples include recording a bank account and a deposit held in it as two separate assets, or valuing an entire business while also counting its equipment or accounts separately. This makes capital appear larger than it is.
Separate personal capital from business assets
A company's assets are not its owner's personal assets. For a personal balance sheet, it makes more sense to estimate the economic value of your ownership stake than to include all the company's property.
Record the valuation date
Stocks valued at today's prices alongside property valued three years ago create misleading proportions. Put a date next to every valuation.
Equity structure and trends: why changes matter
A snapshot shows where you are now. A trend shows where you are going. Recording net worth and its structure monthly or quarterly reveals what is driving changes: new contributions, rising prices, debt repayments or new loans.
For example, net worth rose by 15% over a year, but almost all the growth came from revaluing an apartment, while the share of liquid assets fell. This shows capital growing while financial flexibility weakens. Strum's investment tracker keeps a history of value and allocation, making these changes visible on a chart.
Is there an optimal capital structure for a private investor?
There is no universal ratio. Companies have approaches to finding an optimal structure based on the cost and mix of capital. For a private investor, what matters more is that the structure fits several factors:
- Financial goals. Saving for retirement and buying a home in three years require different assets.
- Horizon. A longer time frame allows more exposure to assets with higher volatility.
- Liquidity needs. Some capital should be accessible quickly, without selling at an unfavourable price.
- Risk tolerance and capacity. Willingness to accept fluctuations and the financial ability to withstand them are different things.
- Debt burden. The higher the share of borrowed capital, the more strongly a fall in asset value affects net worth.
- Future cash flows. If you will need payments soon, some capital should generate income or be held in stable instruments.
Checklist: can you see the real structure of your capital?
- Are all assets gathered in one place?
- Is each asset valued at its current worth?
- Are all loans and other liabilities included?
- Can you see which assets were bought with borrowed funds?
- Have you avoided double counting?
- Are assets converted into one base currency?
- Can you see the currency and geographic breakdown?
- Can you see the share of liquid and illiquid assets?
- Have you accounted for potentially large obligations?
- Are changes in the structure tracked over time?
This material is for informational purposes and is not investment advice. You make your own investment decisions.